Categories
Probate Real Estate, Probate Tips, Purchasing, Seller TipsPublished October 14, 2026
What Is Home Equity and How Can You Use It?
Your home can be more than a place to live. Over time, it may also become an important financial asset.
That value is often described as home equity. Understanding how equity works can help homeowners make more informed decisions about selling, buying another property, refinancing, renovating, or planning for future financial goals.
Home equity is not cash automatically available in your bank account. It is the portion of your home’s value that you own after accounting for what you still owe on your mortgage and any other liens secured by the property.
Here is a clear look at what home equity is, how it is calculated, what can affect it, and some common ways homeowners may choose to use it.
What Is Home Equity?
Home equity is the difference between your home’s current estimated market value and the amount you still owe on your mortgage or other property-related debt.
A simple formula looks like this:
Estimated Home Value - Mortgage Balance - Other Liens = Estimated Home Equity
For example, if your home may be worth $600,000 and you owe $350,000 on your mortgage, your estimated equity would be $250,000 before considering any other liens, selling costs, or transaction expenses.
That does not necessarily mean you would receive $250,000 in cash if you sold. A sale may involve closing costs, mortgage payoff amounts, taxes, repairs, concessions, commissions, and other expenses. But it gives you a starting point for understanding your ownership position.
How Does Home Equity Build?
Home equity can grow in several ways.
Paying Down Your Mortgage
Each mortgage payment may reduce your loan balance over time, depending on your loan terms. As the amount you owe decreases, your ownership share of the home may increase.
Early in many mortgage loans, a larger portion of the payment may go toward interest. Over time, more of the payment may go toward principal. Your lender can provide details about your loan balance and payment structure.
Home Appreciation
If your home’s market value increases, your equity may increase as well.
Market value can be influenced by many factors, including:
- Recent sales of comparable homes
- Buyer demand and available inventory
- Interest rates and affordability
- Property condition
- Location and lot characteristics
- Improvements to the home
- Changes in the surrounding market
Appreciation is never guaranteed. Home values can rise, level off, or decline depending on market conditions.
Improvements and Maintenance
Some improvements may make a home more appealing to future buyers. Projects such as updating kitchens or bathrooms, replacing major systems, improving curb appeal, or addressing deferred maintenance can affect marketability.
However, not every improvement produces a dollar-for-dollar increase in value. A project may still be worthwhile if it improves your enjoyment of the home, reduces maintenance concerns, or helps the property compete more effectively when it is time to sell.
Making Additional Principal Payments
Some homeowners choose to make extra payments toward their mortgage principal. If permitted under the loan terms, this can reduce the loan balance faster and may increase equity over time.
Before making extra payments, it can be helpful to review your broader financial goals and speak with a qualified financial or lending professional.
How Can You Estimate Your Home Equity?
To estimate your equity, you need two main pieces of information:
- Your current mortgage payoff amount
- A realistic estimate of your home’s current market value
Your mortgage payoff amount may be different from the balance shown on a monthly statement because it can include interest through a specific date and other applicable charges. Your lender can provide an official payoff quote when needed.
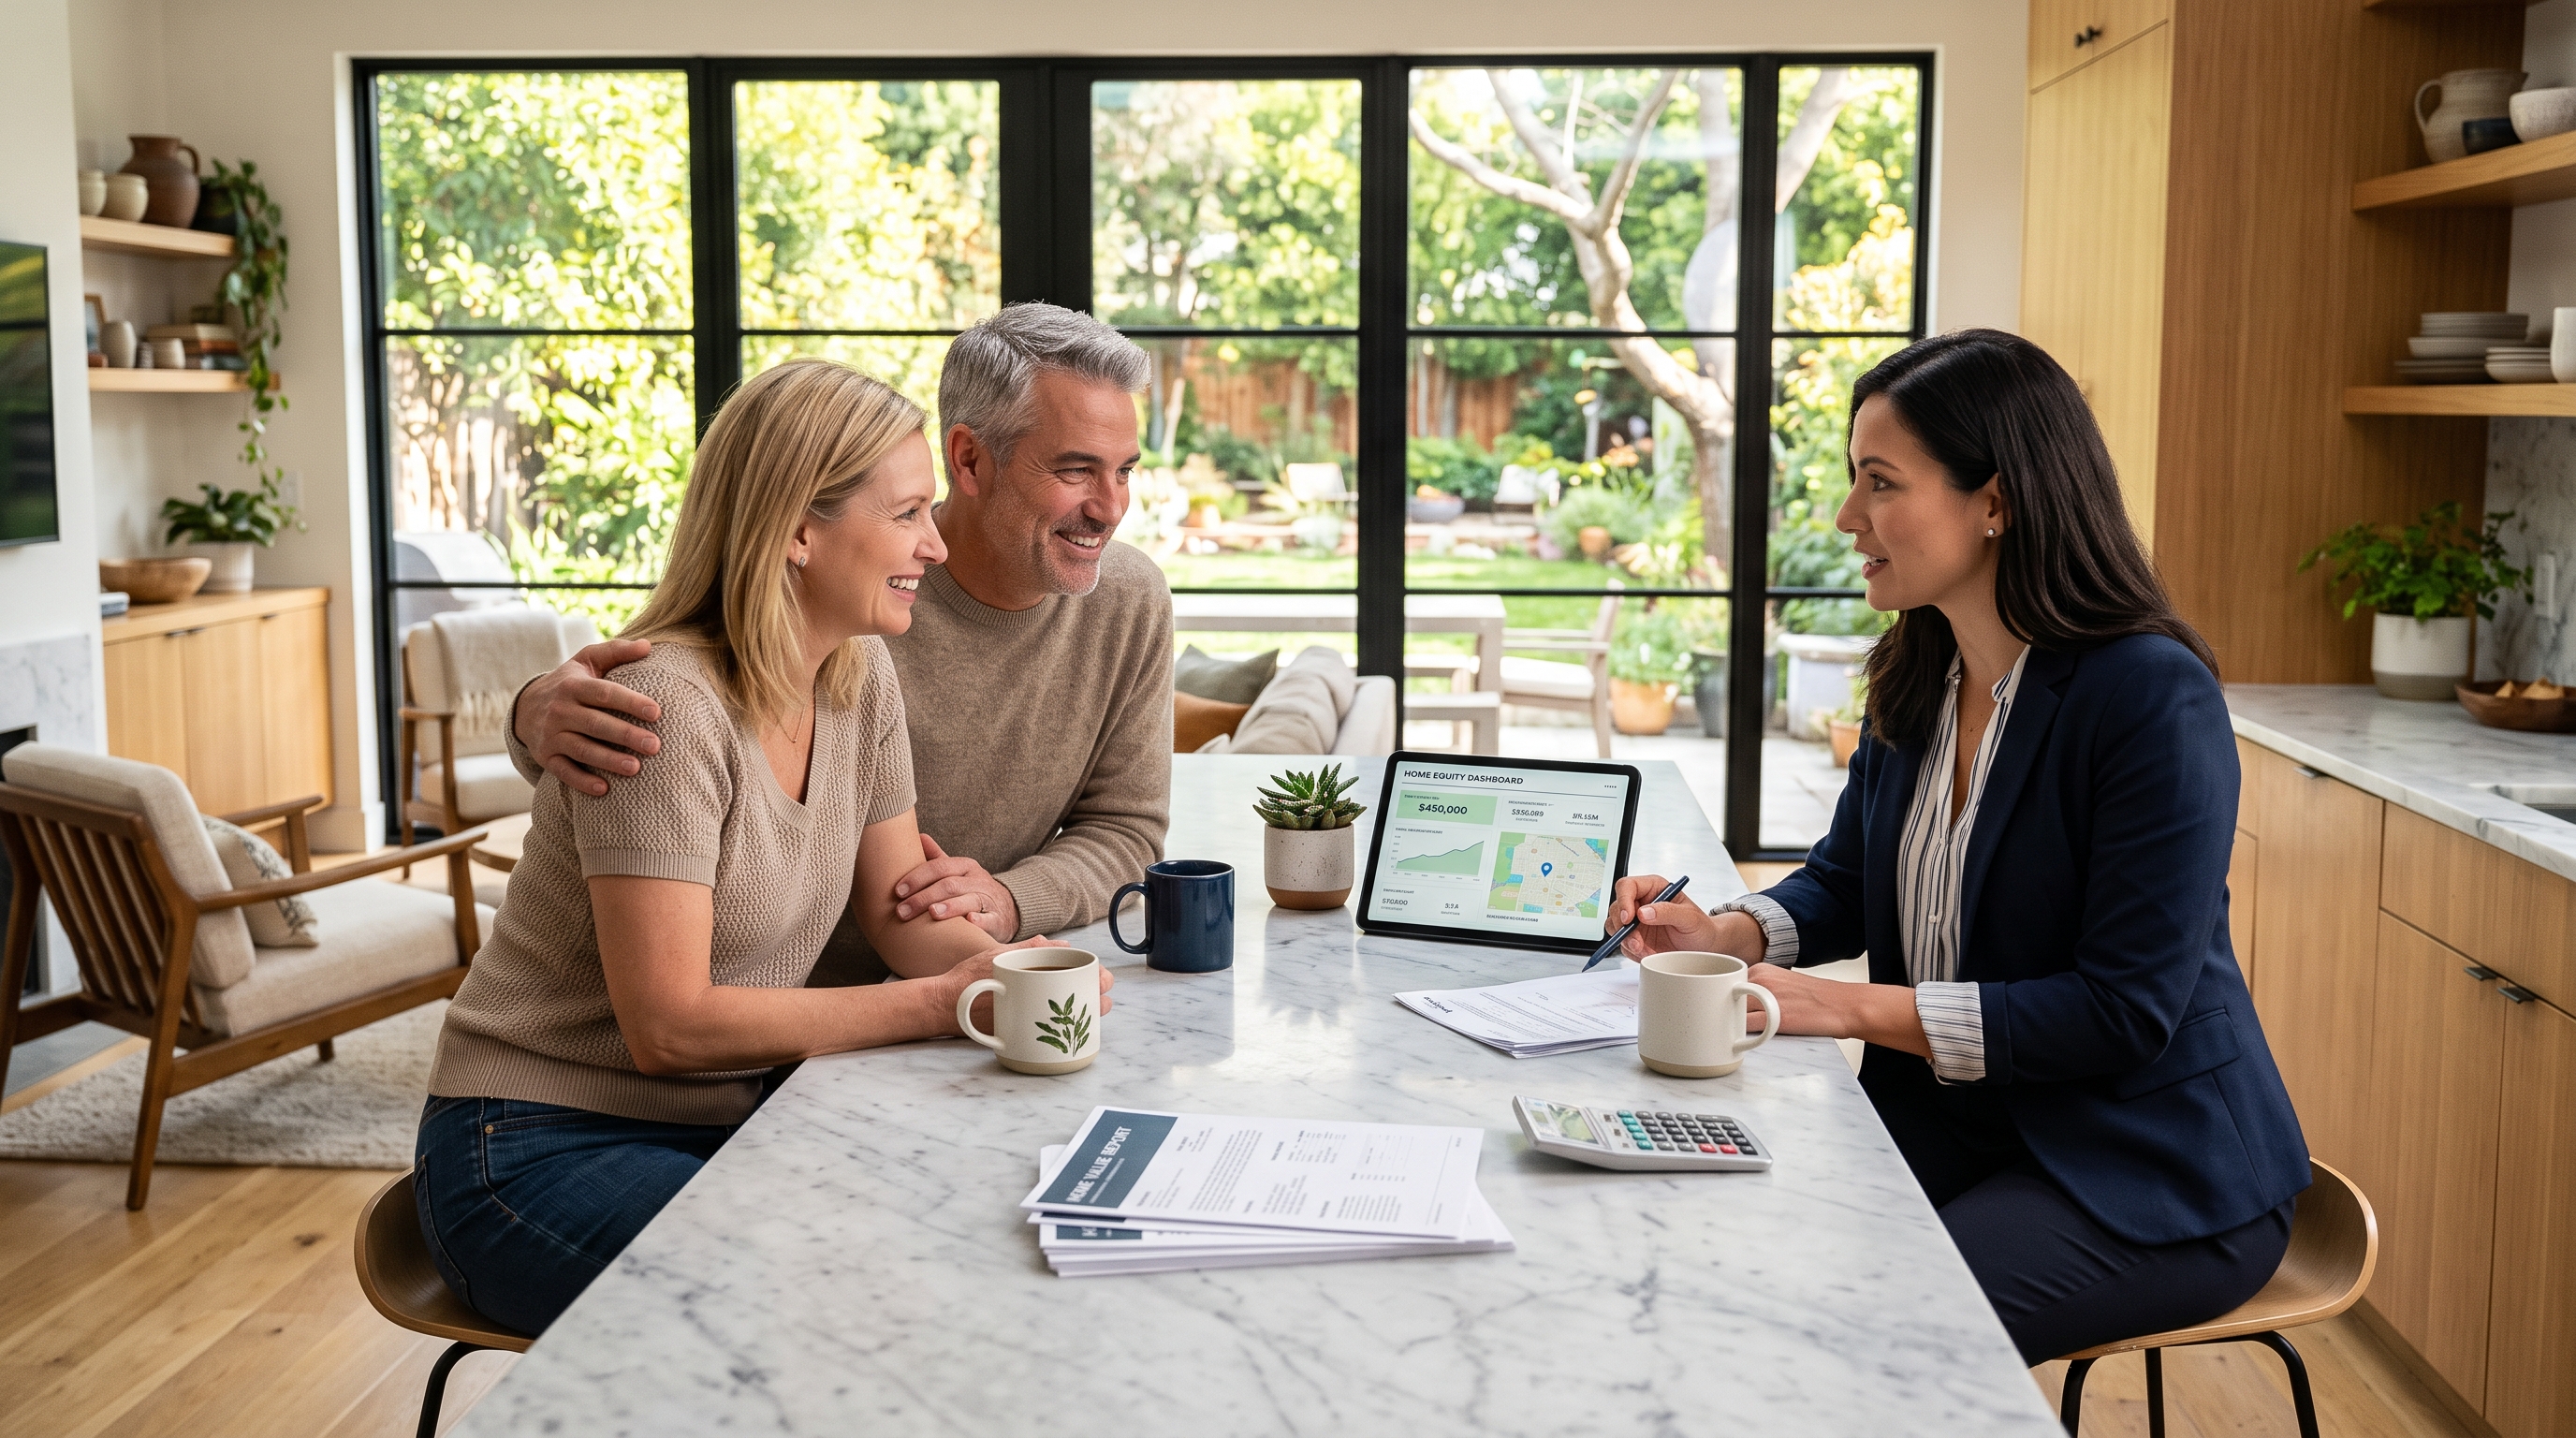
For your home’s value, you may look at online estimates, recent nearby sales, or a comparative market analysis from a real estate professional.
Online estimates can be useful as a starting point, but they may not fully account for your home’s condition, upgrades, lot, layout, location, or current competition. A comparative market analysis can provide a more tailored view of how your property may fit into the current market.
Home Equity Is Different From Sale Proceeds
It is easy to confuse equity with the amount you may receive after selling. They are related, but they are not the same.
Your estimated equity is based on your home’s value minus what you owe. Your estimated net proceeds from a sale may also account for expenses such as:
- Mortgage payoff
- Property taxes or prorations
- Closing costs
- Real estate commissions
- Seller concessions, if negotiated
- Repairs or credits
- Liens or other obligations tied to the property
- Moving costs or preparation expenses
A real estate professional can help you estimate potential sale proceeds based on a likely price range and the costs that may apply to your transaction.
Common Ways Homeowners May Use Equity
Every homeowner’s situation is different. Equity can create options, but using it should be considered carefully.
Selling and Using Equity for Your Next Home
Many homeowners use equity from a sale toward the down payment on their next property.
This may be helpful if you are:
- Moving to a larger home
- Downsizing
- Relocating
- Buying a home in a different market
- Transitioning to a property that better fits your current lifestyle
Before making a move, it helps to understand your estimated net proceeds, your next-home budget, and the timing involved in selling and buying.
Refinancing
Some homeowners refinance to change their mortgage terms, adjust their interest rate, or access equity through a cash-out refinance.
A cash-out refinance replaces your existing mortgage with a new loan that may be larger than your current balance. The difference may be available to you in cash, subject to lender requirements and approval.
Refinancing can involve costs, qualification requirements, and changes to your loan terms. It is important to compare options carefully with a qualified lender.
Home Equity Loan or Home Equity Line of Credit
A home equity loan or home equity line of credit, often called a HELOC, may allow eligible homeowners to borrow against a portion of their equity.
A home equity loan generally provides a lump sum. A HELOC may provide a revolving line of credit, subject to its terms and limits.
These products can be used for a variety of purposes, but they also create additional debt secured by your home. Before borrowing, understand the interest rate, repayment terms, fees, payment changes, and risks involved.
Funding Home Improvements
Some homeowners use equity to fund repairs, maintenance, or renovations.
This may include projects such as:
- Replacing a roof or HVAC system
- Updating kitchens or bathrooms
- Improving accessibility
- Repairing structural or safety concerns
- Adding usable living space
- Improving landscaping or exterior condition
Before borrowing for improvements, consider whether the project supports your goals, budget, and expected length of ownership.
Consolidating Debt
Some homeowners consider using equity to consolidate higher-interest debt. This can simplify payments in some situations, but it also changes unsecured debt into debt secured by the home.
That decision should be made carefully with qualified financial guidance. Missing payments on a loan secured by your home can have serious consequences.
Planning for Retirement or a Lifestyle Change
Equity may play a role in retirement planning, downsizing, relocating closer to family, or reducing housing expenses.
For example, a homeowner may sell a larger property and use the proceeds to purchase a smaller home, rent, or create more financial flexibility. The right choice depends on housing needs, taxes, health considerations, lifestyle goals, and long-term financial planning.
What Can Reduce or Limit Your Equity?
Equity can change over time. It is not guaranteed to increase.
Factors that may reduce or limit equity include:
- A decline in local home values
- Taking on additional loans secured by the property
- Deferred maintenance or property damage
- Selling costs and transaction expenses
- Liens, unpaid taxes, or other obligations
- A mortgage balance that remains high relative to the home’s value
This is why it is helpful to review your equity periodically, especially before making a major financial or real estate decision.
Questions to Ask Before Using Home Equity
Before selling, refinancing, borrowing, or making a major investment in your home, consider asking:
- What is my estimated home value today?
- What is my current mortgage payoff amount?
- Are there any liens or obligations tied to the property?
- What would my estimated net proceeds be if I sold?
- What are the costs and risks of borrowing against my home?
- How would this decision affect my monthly budget?
- Does this support my short-term and long-term goals?
- Should I speak with a lender, tax professional, attorney, or financial advisor?
The answers can help you make a decision based on your full financial picture, not just an estimated value number.
A Simple Home Equity Checklist
Use this checklist when reviewing your equity position:
- Request your current mortgage balance or payoff information.
- Review recent comparable home sales in your area.
- Consider your home’s condition, improvements, and maintenance needs.
- Identify any liens, second mortgages, or home equity loans.
- Estimate potential selling costs if a move may be in your future.
- Review your monthly budget before taking on new debt.
- Speak with qualified professionals about lending, tax, legal, or financial questions.
- Create a plan that aligns with your goals for the next one to five years.
Work With Legacy Realty Partners
If you are curious about your home’s current market position, Legacy Realty Partners can help you understand the real estate side of the equation.
Our team can review recent comparable sales, discuss your home’s condition and improvements, and help you estimate what a sale could look like based on current market conditions. Whether you are considering selling soon, planning a future move, or simply want to understand your options, we are here to help you make a more informed plan.
Contact Legacy Realty Partners to start a personalized home-value conversation.
Important Disclaimer
This article is provided for general informational purposes only and should not be considered legal, tax, lending, appraisal, or financial advice. Home values, mortgage balances, lending requirements, interest rates, and transaction costs can change. No estimate, comparative market analysis, appraisal, or calculation guarantees a future sale price, loan approval, or financial outcome. Consult qualified lending, legal, tax, appraisal, and financial professionals for guidance specific to your situation.
Danny Gomes
Realtor / Probate Specialist | Legacy Realty Partners | Danny Gomes | PLACE
or another way