Categories
PurchasingPublished September 30, 2026
What Costs Should Buyers Plan for Beyond the Down Payment? A Complete Budgeting Guide
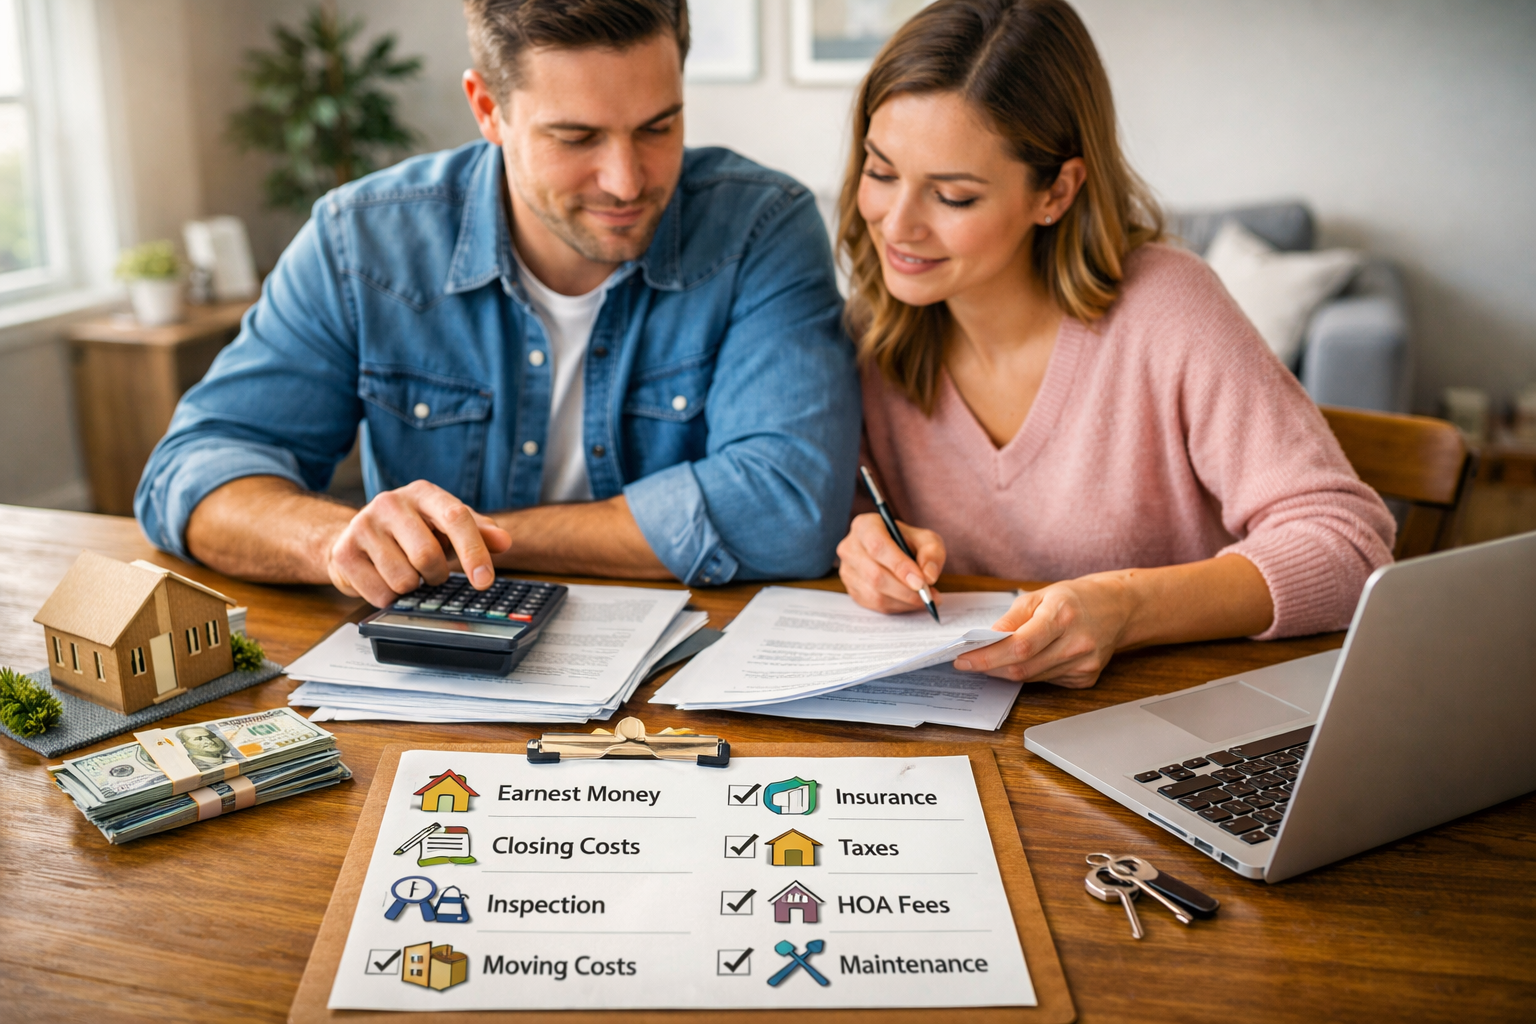
For many homebuyers, the down payment gets most of the attention. It is a major part of the purchase, but it is not the only expense that matters. Buyers should also prepare for several other upfront and ongoing costs that can affect how affordable a home feels before, during, and after closing.
If you are planning to buy a home, building a realistic budget can help you avoid surprises and make stronger decisions throughout the process. The exact costs will vary based on your location, loan program, contract terms, property type, insurance needs, and what is negotiated between the parties. In some cases, certain expenses may be reduced through seller credits or, where permitted, rolled into financing. In other cases, they must be paid out of pocket.
Here is a clear breakdown of the costs buyers should plan for beyond the down payment.
1. Earnest Money Deposit
Earnest money is a deposit a buyer submits after a seller accepts an offer. It shows good faith and demonstrates that the buyer is serious about moving forward.
This money is typically held in escrow and is often applied toward the buyer’s funds due at closing. The amount can vary depending on the market, the purchase price, local custom, and the terms negotiated in the contract.
Buyers should understand:
- When the earnest money is due
- How much is required under the contract
- Under what circumstances it may be refundable or at risk
Because contract deadlines and contingencies matter, buyers should review earnest money terms carefully with their real estate agent and any appropriate legal or financial professionals.
2. Closing Costs
Closing costs are the collection of fees and charges required to complete the transaction. These costs can come from the lender, title or escrow company, government recording offices, and other service providers involved in the sale.
Closing costs vary widely by location, loan type, purchase price, and service providers. They may also be affected by negotiations, including whether the seller agrees to contribute credits toward allowable buyer costs.
Common closing costs may include:
- Lender-related fees
- Appraisal fees
- Title and escrow charges
- Recording-related charges where applicable
- Prepaid taxes and insurance
- Escrow reserve funding if required by the lender
Buyers should ask for a detailed estimate early and compare it with final figures before closing.
3. Lender Fees
Your mortgage lender may charge a variety of fees connected to processing, underwriting, and funding the loan. These charges depend on the lender, the loan program, and the complexity of the file.
Lender fees may include items such as:
- Application or administrative fees
- Underwriting or processing fees
- Credit report fees
- Rate lock-related charges, if applicable
- Discount points, if the buyer chooses to pay for a lower interest rate
Not every lender structures fees the same way, so buyers should review loan estimates carefully and ask questions about what is optional, what is required, and what may change before closing.
4. Appraisal
When financing a home purchase, the lender will often require an appraisal to estimate the property’s market value. The buyer commonly pays this cost, although exact practices can vary.
The appraisal is important because it helps the lender confirm that the property supports the loan amount. If the appraised value comes in lower than the purchase price, the buyer may need to renegotiate, bring in additional funds, or explore other options depending on the contract and loan guidelines.
Appraisal costs vary by property type, location, and complexity.
5. Home Inspection and Specialized Inspections
A general home inspection is one of the most important buyer expenses to plan for. It gives buyers a professional evaluation of the home’s visible condition and can help identify issues before closing.
Depending on the property, buyers may also choose or need specialized inspections, such as:
- Pest or termite inspections
- Sewer scope inspections
- Roof inspections
- Foundation or structural evaluations
- Mold inspections
- Radon testing where relevant
- HVAC, chimney, pool, septic, or well inspections where applicable
These costs vary based on the property’s age, condition, systems, location, and buyer concerns. While inspections add to upfront expenses, they can help buyers make more informed decisions about repairs, negotiations, or whether to proceed.
6. Title, Escrow, and Recording-Related Charges
Most transactions involve third parties who help manage funds, documents, and the legal transfer of ownership. Depending on the area and transaction structure, buyers may encounter charges related to title services, escrow services, settlement handling, notary services, and recording-related fees.
These costs can vary significantly by state, county, local custom, and contract terms. In some markets, certain charges are more commonly paid by the seller, while in others they may be split or paid by the buyer.
Because practices differ, buyers should review their closing disclosures carefully and ask which charges are customary, negotiable, or required in their transaction.
7. Prepaid Items and Escrow Reserves
At closing, buyers may need to prepay certain housing expenses and deposit funds into reserve accounts. These are not always lender fees in the traditional sense, but they still affect the amount of cash needed to close.
Examples may include:
- Prepaid mortgage interest
- Initial homeowners insurance premium
- Property tax prepayments
- Escrow reserves for taxes and insurance if the lender requires an impound or escrow account
The amount needed depends on the closing date, tax cycle, insurance premium, lender requirements, and local billing practices.
8. Homeowners Insurance
Homeowners insurance is typically required by lenders before closing on a financed purchase. Even cash buyers should budget for coverage that fits the property and their risk tolerance.
Insurance costs can vary based on:
- Location
- Home value and replacement cost
- Property age and condition
- Coverage selections and deductibles
- Claims history and insurer underwriting standards
Some properties may also require or benefit from additional coverage, depending on the risks involved. Buyers should shop for quotes early so insurance costs do not become a last-minute surprise.
9. Property Taxes
Property taxes are an ongoing ownership cost that buyers should factor into their monthly and annual housing budget. At closing, buyers may also need to prepay taxes or contribute to escrow reserves, depending on the timing of the transaction and lender requirements.
Tax amounts vary by jurisdiction and property assessment practices. They may also change over time. Buyers should avoid assuming that a seller’s current tax bill will always match their future obligation.
10. HOA or Condo Fees
If the property is part of a homeowners association, condominium association, or similar community structure, buyers should budget for recurring dues and any applicable transfer-related charges.
These fees can cover shared amenities, exterior maintenance, insurance for common areas, management, reserves, and other community expenses. The amount and scope vary by property type and association.
Buyers should also ask whether there are pending assessments, move-in fees, application fees, or other association-related costs that could affect their budget.
11. Moving Costs
Moving expenses are easy to underestimate. Whether you hire professional movers or handle the move yourself, there are usually costs involved.
Potential moving expenses include:
- Moving company charges
- Truck rental
- Packing supplies
- Storage fees
- Utility connection or transfer charges
- Travel expenses if relocating from another area
The total depends on distance, timing, volume of belongings, and whether specialty items require extra handling.
12. Immediate Repairs, Replacements, and Furnishings
Even after a successful inspection and closing, many buyers spend money soon after move-in. Some purchases are planned, while others come up unexpectedly.
Common post-closing expenses may include:
- Paint, flooring, or cosmetic updates
- Appliance replacement
- Locks, security upgrades, or smart home devices
- Window coverings
- Furniture
- Yard tools or landscaping supplies
- Minor repairs discovered after occupancy
These costs vary based on the condition of the home, what is included in the sale, and the buyer’s preferences. Setting aside a move-in cushion can help reduce stress.
13. Ongoing Maintenance and Utilities
Owning a home means taking responsibility for regular upkeep and monthly services. Buyers should think beyond the mortgage payment and plan for the true cost of ownership.
Ongoing expenses may include:
- Electricity, gas, water, sewer, trash, and internet
- Routine HVAC servicing
- Lawn care or snow removal
- Pest control
- Gutter cleaning
- General repairs and maintenance
- Longer-term replacement planning for roofs, water heaters, appliances, and major systems
Property type matters here. A single-family home may have different maintenance demands than a condo or townhome, even if some exterior items are covered by association dues.
What Costs Can Vary Most?
Nearly every buyer will face costs beyond the down payment, but the exact amount depends on several factors. The biggest variables often include:
- Location: Taxes, insurance, title practices, recording-related charges, and service pricing can differ by market.
- Loan program: Different financing options may have different fee structures, reserve requirements, mortgage insurance obligations, and rules about what can be financed.
- Contract terms: Negotiated repairs, credits, timelines, and contingency terms can affect out-of-pocket costs.
- Property type: Condos, townhomes, single-family homes, and rural properties may involve different inspections, dues, insurance needs, or maintenance expectations.
- Negotiation outcomes: In some transactions, seller credits may help offset allowable closing costs. In limited situations and only where permitted, certain costs may be rolled into financing. Not every cost is financeable, and not every loan program allows the same flexibility.
Because of these variables, buyers should avoid relying on generic estimates alone.
Practical Budgeting Checklist for Buyers
Use this checklist to build a more complete homebuying budget:
- Estimate your down payment
- Set aside earnest money funds
- Review projected closing costs from your lender
- Budget for appraisal and inspections
- Get homeowners insurance quotes early
- Ask about property taxes and whether escrow reserves will be required
- Check for HOA or condo dues and any transfer-related fees
- Plan for moving expenses
- Create a move-in fund for repairs, appliances, and furnishings
- Build an emergency reserve for maintenance and utility costs after closing
Buyer Tips to Avoid Budget Surprises
- Ask for estimates early. A lender, real estate agent, and settlement professionals can help you understand likely costs before closing.
- Compare service providers when appropriate. Some fees may vary depending on the lender, insurer, inspector, or other vendor.
- Read the contract carefully. Deadlines, contingencies, and negotiated terms can affect both risk and cost.
- Do not spend your cash reserves too tightly. Keeping extra funds available can help if costs change before closing or repairs arise after move-in.
- Understand what is negotiable and what is not. Some costs may be reduced through seller credits or other negotiations, while others are fixed or limited by lender and regulatory requirements.
- Think beyond closing day. A home that fits your monthly payment still needs to fit your maintenance, utility, and lifestyle budget.
The Bottom Line
The down payment is only one piece of the financial picture. Buyers should also prepare for earnest money, closing costs, lender fees, appraisal, inspections, title and escrow charges, prepaid items, insurance, taxes, association dues where applicable, moving expenses, immediate home setup costs, and ongoing maintenance.
A thoughtful budget can help you shop with more confidence, negotiate more effectively, and transition into homeownership with fewer surprises.
General informational disclaimer: This article is provided for general informational purposes only and should not be considered legal, tax, insurance, lending, or financial advice. Costs, requirements, and available options vary by location, loan program, property, service provider, and transaction terms. Buyers should consult qualified real estate, lending, legal, tax, insurance, and other relevant professionals for guidance specific to their situation.
Work With Legacy Realty Partners
If you are preparing to buy a home and want a clearer picture of the full costs involved, Legacy Realty Partners can help you plan with confidence. Our team can walk you through the buying process, help you understand the expenses that may apply to your situation, and connect you with trusted professionals as you move toward closing.
Connect with Legacy Realty Partners to start your home search and build a smarter buyer budget from day one.
Danny Gomes
Realtor / Probate Specialist | Legacy Realty Partners | Danny Gomes | PLACE
or another way